Wise Review: The Best Online Banking Option? (2026)
What People Are Saying
Wise is an excellent card for travelling. It is so great to be able to have accounts in the currencies of the countries you are visiting saving on bank transaction fees, being able to transfer between them and easier to keep a track of expenditure. The website and app are excellent, so easy to use and intuitive. – Dean HunterKZ
| Results / Outcomes | 4.8 |
| Refund Policy / Guarantee | NA |
| Support & Community | 4.7 |
| Value for Money | 4.8 |
Wise Review: The International Account That Stops Banks From Quietly Taxing Your Money.
You already know the ritual. You send money home, pay a supplier, or cover a trip, and the bank smiles while the exchange rate does the real damage. The fee on the screen looks small. The rate in the footnote does not. By the time the money lands, a quiet slice of it has vanished into a markup nobody asked you to approve.
That gap is the whole business model. Banks and a lot of “cheap” apps do not win by being faster. They win by showing you one number and settling at another. Wise built the opposite habit: the mid-market rate you can check on Google, a fee you see before you confirm, and an account that lets you hold, receive, and spend in more than one currency without pretending a wire is a personality trait.
If you move money across borders more than once a year, this Wise review is the short version of why people stop arguing with their bank and open the app instead.
What Wise actually is
Wise, formerly TransferWise, is a regulated money-moving company, not a high-street bank with a travel brochure. The product that matters for most people is the Wise Account: an international account for sending, spending, and converting money like a local.
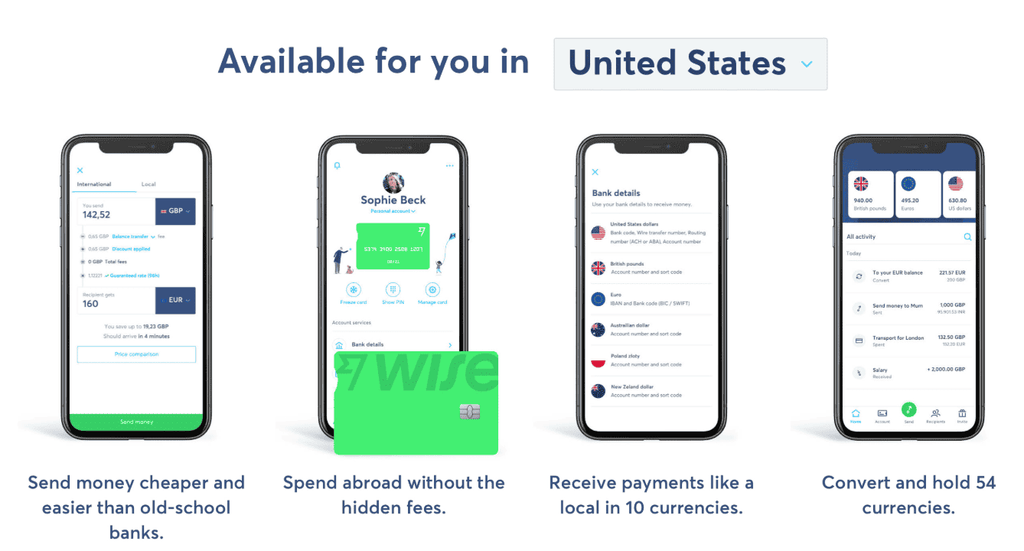
On the current Wise site, the pitch is plain. You can send money abroad to 140+ countries. Most transfers are built for speed: Wise says 74% arrive in under 20 seconds and 95% within a day. You can lock the rate for up to 24 hours, so a lunch break does not become a currency event. Support runs 24/7 by phone, email, or chat.
Wise also says 18.9 million customers, businesses, and banks use it, moving about $16 billion a month, under 65 licences worldwide, with customer money held in safeguarded accounts separate from company funds.
Availability, account details, and interest all depend on where you live. Treat the checkout screen as the source of truth for your corridor. The homepage calculator is a demo, not a promise carved in stone.
Features worth opening the app for
Send money at the real rate
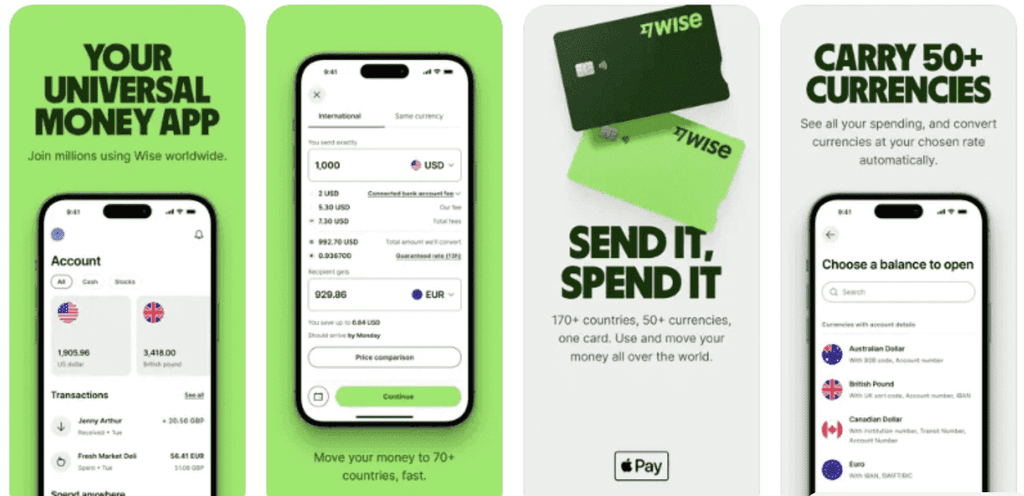
The feature people remember is the rate. Wise uses the mid-market exchange rate and shows its fee up front. Banks and some apps inflate that rate and call the difference “no fee.” Wise would rather you see the fee and keep the rate.
A few details that change how it feels in real life:
- Delivery to 140+ countries, with popular routes often landing the same day or in seconds.
- A rate guarantee of up to 24 hours, so the amount your recipient gets does not drift while you confirm.
- A fee discount when you send larger amounts. Wise flags this above 25,000 USD or the equivalent.
- A live comparison on the site against banks and PayPal, so the gap is visible before you move a cent.
Receive money with local account details
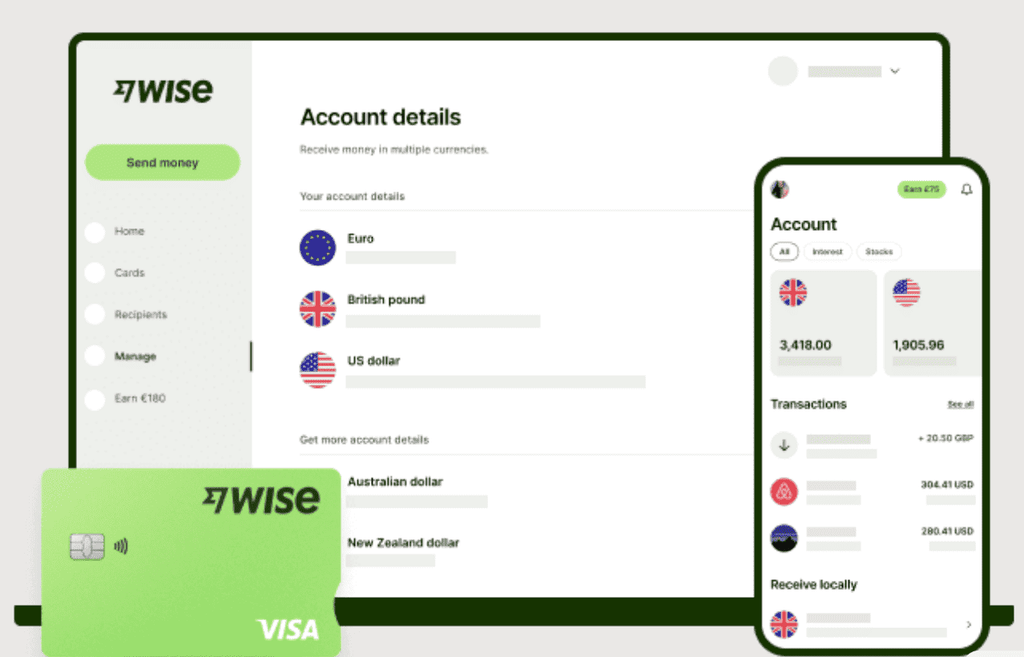
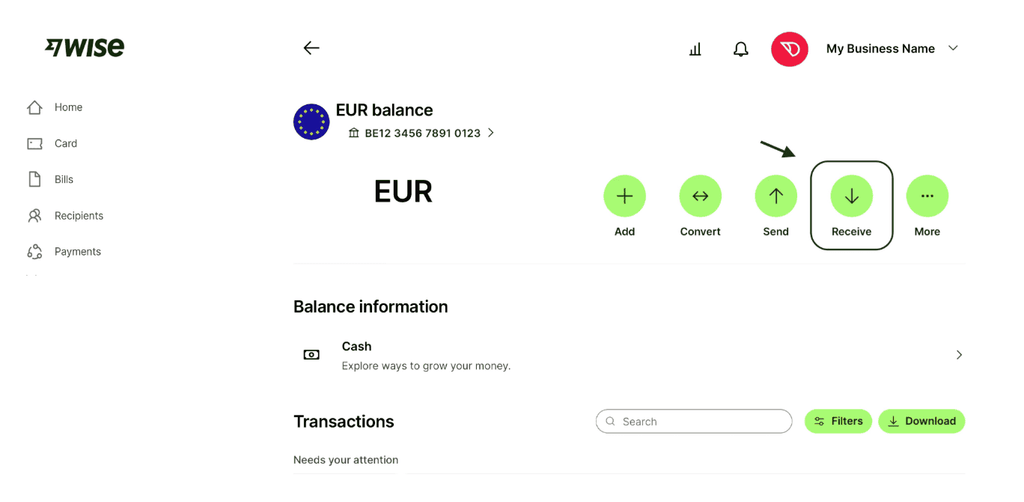
Getting paid from abroad is usually the annoying half. Wise lets eligible customers hold balances and receive with global account details in a long list of currencies, including USD, GBP, EUR, AUD, CAD, NZD, SGD, JPY, and others. A client in London can pay a British account number. A client in the eurozone can pay an IBAN. You are not asking them to “just do an international wire and hope.”
Wise lists receiving details across 22 currencies on its US pages. The exact set depends on your country of residence.
Spend abroad with the Wise card
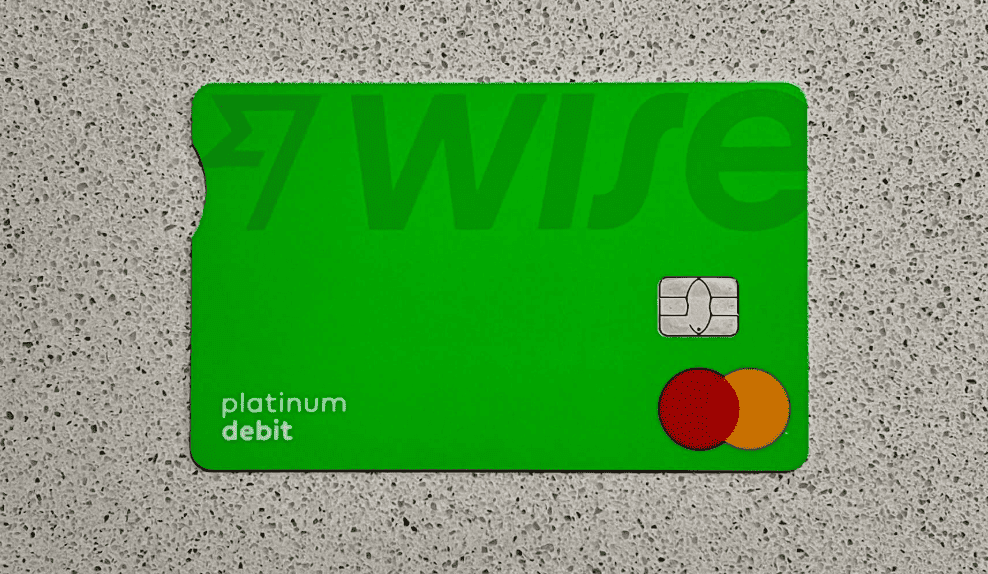
The Wise debit card is the travel piece. Wise says you can pay and withdraw in 215 countries and territories without hidden exchange-rate markups. The card works from the balance you already hold, and you can add it to Apple Pay or Google Pay in supported regions. Order fees vary by country. In the US it is commonly a one-time card fee, not a monthly subscription.
Interest on money you are already holding
Eligible customers can opt in to earn interest on USD, GBP, and EUR balances. As of the rate update Wise published on 18 September 2026, that was 3.4% APY on USD, 2.21% on GBP, and 1.2% on EUR. In the US, opted-in balances can come with passthrough FDIC insurance up to 250,000 USD through Wise’s program bank. Interest is not available to residents of New York and Alaska, and Wise’s help centre also lists Nevada. Money stays accessible. It is not locked in a term product.
A business account if the company is the one crossing borders
Wise Business is the same idea for companies: get paid and pay in 40+ currencies, issue cards, manage team spend, and connect accounting software. Wise says more than 900,000 businesses use it. There is also Wise Platform, which lets banks and larger firms plug into the same network. Most readers will never need the platform. Freelancers and small exporters often need the business account.
Why people switch and stay
The psychology here is simple. People do not leave a bank because an ad was clever. They leave because they finally saw the number. Wise is built around that moment.
- Transparent pricing. The fee is a line item. The rate is the mid-market rate. You can compare it with Google before you tap send.
- Speed on routes that used to take days. A same-day or sub-minute transfer changes how you plan rent, payroll, and family support.
- One account, many currencies. Hold, convert, receive, and spend without opening a local bank account in every country you touch.
- No monthly account fee. Opening and holding money is free. You pay when you convert or send, and you see that cost first.
- Useful for real life, not just one wire. Card spending, local details for invoices, rate locks, and interest on eligible balances make it a habit, not a one-off tool.
- Regulation and safeguards. Licences in many markets, safeguarded funds, and a large fraud-check operation are the boring reasons people trust it with rent money.
A Trustpilot line Wise publishes from a long-time user sums up the pattern: years of monthly transfers, lower cost than a regular bank, less hassle. That is the review that matters. Not a launch-day compliment.
Who Wise is ideal for
Wise is a strong fit if any of these sound like your month:
- Expats and families sending support, rent, or savings between countries on a schedule.
- Freelancers and remote workers who invoice in USD, EUR, or GBP and want to get paid like a local.
- Travellers and people abroad for months, who would rather spend from a held balance than pay a card markup at every cafe.
- Small businesses and startups paying contractors or suppliers in several currencies.
- Anyone comparing a bank wire with a Wise quote and noticing the recipient gets more on the same send amount.
It is especially easy to justify once you send more than a few hundred dollars. The rate difference compounds. A one-off 50-dollar gift can go through almost anything. A monthly transfer, a client payment, or a trip budget should not.
If your life is entirely domestic and you never convert currency, a local bank account is enough. Wise is for the part of your money that crosses a border.
What to know before you open an account
Wise is clearest when you use it for what it is built to do.
- Fees vary by corridor, amount, and how you pay. A card payment usually costs more than a local bank transfer. The quote shows this before you confirm.
- Account details, card perks, ATM allowances, and interest depend on your country. Check the pricing page for your region rather than a review written for one market.
- Large balances you want fully inside a traditional bank deposit-guarantee scheme may still sit better at a bank. Wise safeguards funds, and the US interest feature adds passthrough FDIC cover only when you opt in, up to the stated limit.
- The app is the product. If you want a branch and a person who already knows your dog’s name, this is not that shop. Support is there around the clock. It is not a marble lobby.
None of that changes the core trade. You see the rate. You see the fee. The recipient gets the amount on the screen.
Wise Review: Conclusion
A good Wise review ends where the bank transfer usually starts: with the amount that actually arrives. Wise wins because it refuses the hidden markup, shows a mid-market rate, and wraps that honesty in an account you can receive into, spend from, and, if you are eligible, earn interest on.
Open a quote for the route you actually use. Compare it with your bank on the same amount. If the recipient gets more, and the money lands in seconds or the same day, you already have the answer. Sign up, hold the currency you need, and let the next transfer be boring in the best way.
Rates, fees, and eligibility change. Confirm the live quote on wise.com before you send.